The Quick Version
- The retirement income exclusion lets each Georgia taxpayer 65 or older subtract up to $65,000 of retirement income for 2026, and $35,000 from 62 to 64.
- Each spouse has a separate limit. Room one spouse leaves unused cannot shift to the other.
- Social Security stays outside the calculation, so it never eats into the $65,000.
- Cabin rental income that owes self-employment tax counts as earned income, capped at $5,000.
- The 65-and-older limit rises to $70,000 in 2027.
- Last updated September 2026.
For the 2026 tax year, Georgia lets each resident 65 or older subtract up to $65,000 of retirement income before its flat 4.99% rate applies. Used in full, that is worth $3,243.50 of state tax a year per person, and $6,487 for a married couple who both qualify.
The rule is statewide, so a retiree in Blue Ridge works from the same worksheet as one in Atlanta. What differs in the North Georgia mountains is the income people here tend to have: cabin rent, land and home-sale gains.
Whether you collect the full amount turns on whose name that income arrives in, what kind it is, and when you became a Georgia resident. This is general information rather than tax advice, so run your own return past a CPA.
How much is the retirement income exclusion worth in 2026?
Up to $3,243.50 per taxpayer. The Georgia Department of Revenue sets the exclusion at $35,000 from 62 through 64 and $65,000 at 65 or older. A taxpayer under 62 who is permanently disabled, to the point of being unable to do any gainful work, reaches the $35,000 tier, and the return has to carry the date of disability.
| Who qualifies | 2026 exclusion | Georgia tax it removes at 4.99% | From 2027 |
|---|---|---|---|
| Age 62 to 64 | $35,000 | $1,746.50 | $35,000 |
| Under 62 and permanently disabled | $35,000 | $1,746.50 | $35,000 |
| Age 65 or older | $65,000 | $3,243.50 | $70,000 |
| Married, both 65 or older | $130,000 | $6,487.00 | $140,000 |
The 2027 step comes from House Bill 463, which also set this year’s 4.99% rate. The dollar values assume every excluded dollar would otherwise be taxed at that rate, so read them as ceilings rather than a promise.
Can a married couple pool the exclusion?
No. Each spouse must qualify on their own and claims only against income that belongs to them. The Department’s IT-511 instruction booklet assigns every item to the person who owns it, and splits anything held jointly 50% to each. On a joint return, ownership matters as much as age.
Take a hypothetical couple, the Hales. He is 67 and draws an $80,000 pension in his own name. She is 63 and takes $10,000 a year from her IRA. Their joint brokerage account pays $12,000 of dividends, so $6,000 lands on each side of the return.
| The Hales, 2026 | Him, 67 | Her, 63 |
|---|---|---|
| Retirement income | $86,000 | $16,000 |
| Exclusion available | $65,000 | $35,000 |
| Exclusion used | $65,000 | $16,000 |
| What is left | $21,000 taxable | $19,000 unused |
Georgia taxes his $21,000 at 4.99%, or $1,047.90, while $19,000 of her room goes to waste. Nothing on the form lets her spare room absorb his pension. Whether any income-producing asset belongs in her name is a question for your CPA before anything is retitled.
What happens when you sell a house after 62?
Most of the gain never reaches Georgia. The state starts from federal adjusted gross income, and the IRS lets a seller exclude up to $250,000 of gain on a main home, or $500,000 on a joint return, after owning and living in it for at least two of the last five years, per IRS Topic 701.
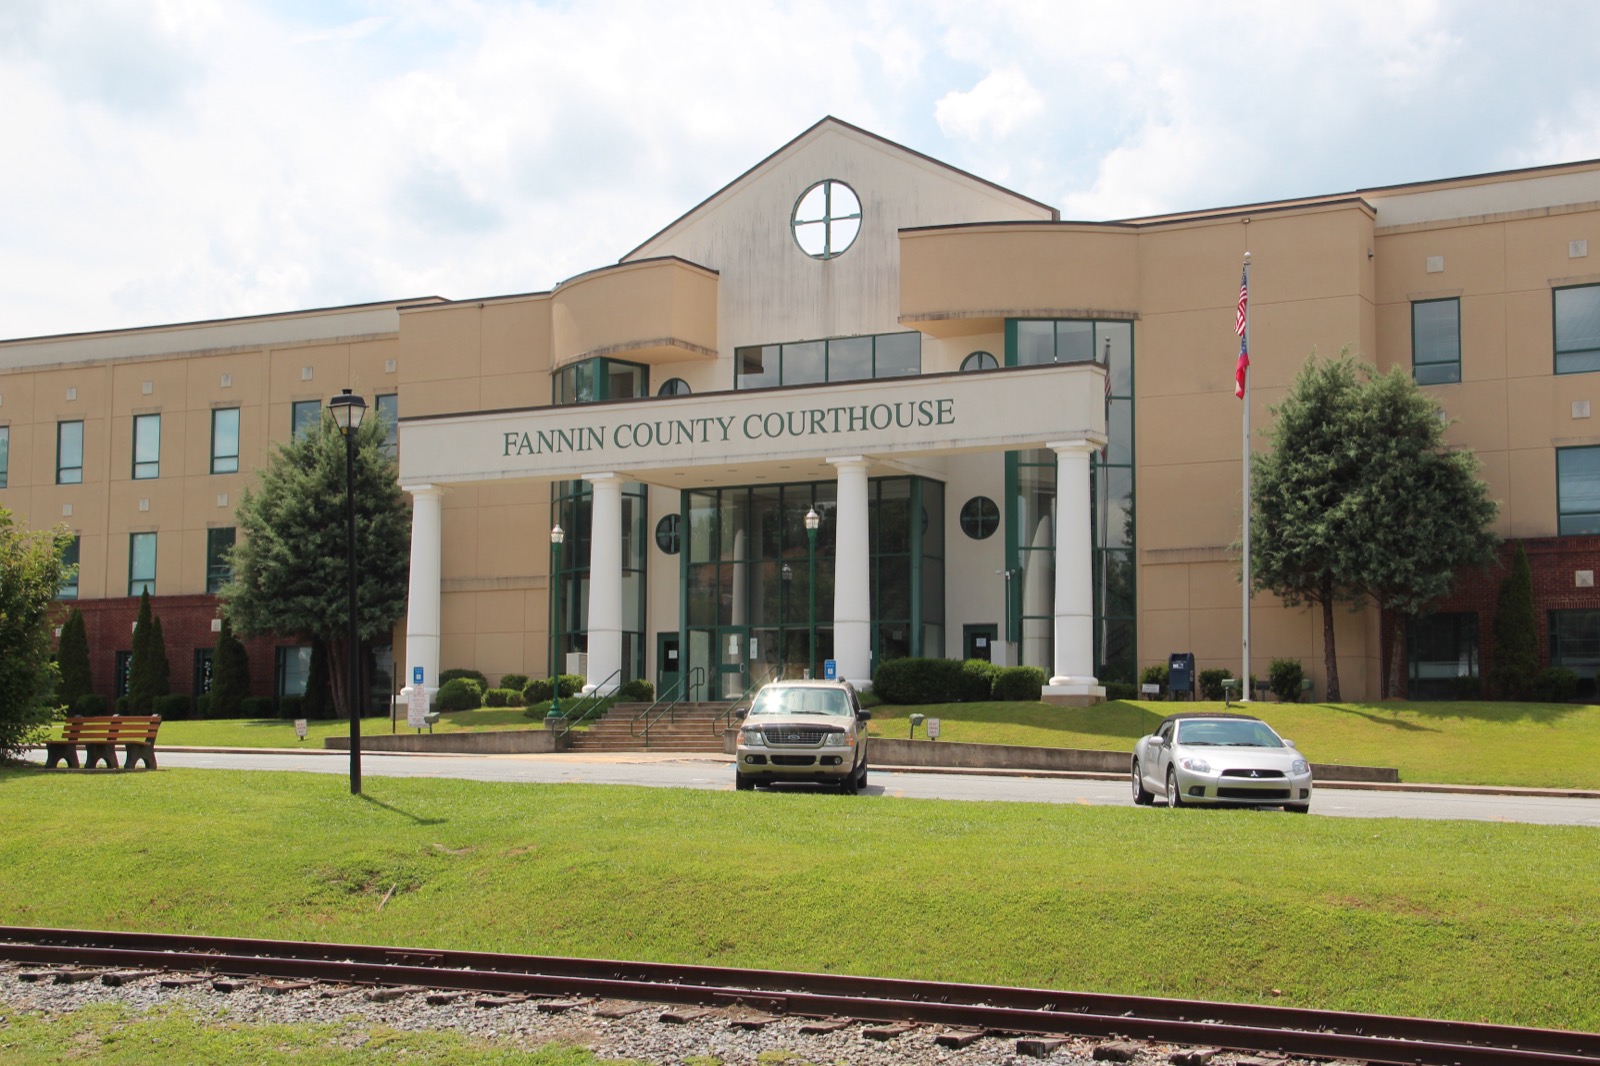
Gain above that line is capital gain, and capital gains count as retirement income. Local prices make that relevant. Fannin County’s single-family median sale price was $650,000 across the first seven months of 2026, and $815,000 in July alone, per the Georgia Association of Realtors. At those prices a long-held home can produce a gain larger than the federal exclusion.
Say a couple, both 66, sell the Blue Ridge home they have lived in for 20 years at a $620,000 gain. The federal exclusion takes $500,000. The other $120,000 splits $60,000 to each, and if neither has other retirement income that year, each $65,000 exclusion absorbs its half. The sale adds no Georgia tax.
At the 4.99% rate, a couple aged 60 would owe about $5,988 on the same $120,000. A pension in the same year shrinks the room dollar for dollar, which makes a large sale worth timing with a CPA.
Do IRA withdrawals and Roth conversions count?
Yes to both. The Department’s exclusion worksheet carries a line for taxable IRA distributions beside the one for pensions, and the Form 1040 instructions report a Roth conversion as a taxable IRA distribution. Qualified Roth withdrawals are not taxed federally, so they never enter the calculation.
That turns unused exclusion into a planning tool. A 66-year-old with a $22,000 pension has $43,000 of room left. Converting $43,000 from a traditional IRA to a Roth adds nothing to the Georgia bill, where a 60-year-old would owe about $2,145.70 on the same conversion at 4.99%. The federal tax on it does not change, which is why the decision belongs with your CPA.
Does a cabin rental in the North Georgia mountains count?
Usually, and in full. Net rental income is on the Department’s list of qualifying retirement income, so a 66-year-old netting $40,000 from a rental cabin can shelter all of it inside a $65,000 exclusion.
The exception is the one that catches short-term rental owners. If rental income is subject to self-employment tax, the IT-511 booklet moves it onto the earned-income line, where only $5,000 can use the exclusion. The IRS sends a rental to Schedule C, as business income, when the owner provides substantial services primarily for the tenant’s convenience, per IRS Topic 414.
Run the same $40,000 through that door and $35,000 falls outside the exclusion, or $1,746.50 of Georgia tax. Selling the cabin works differently again: a second home gets no federal home-sale exclusion, but its gain is still capital gain inside the Georgia one.
What if you move to Georgia partway through the year?
You get a smaller exclusion. Part-year residents must prorate it, and the booklet prorates earned and unearned income separately, each by its Georgia-source share. In the Department’s own worked example, a $65,000 maximum shrinks to $34,785, made up of $1,647 on the earned side and $33,138 on the unearned side.
That is a move I know well, since I keep homes in both Fort Lauderdale and Blue Ridge. Florida has no personal income tax, so pension checks received before the move were never taxed there, and after it only the Georgia-source share earns exclusion. The earlier in the year the move happens, the larger that share tends to be.
What sits outside the retirement income exclusion?
Four things. Social Security, which Georgia exempts separately on Schedule 1 of Form 500, per the Department’s retiree FAQ. Interest on U.S. government bonds and other income Georgia does not tax, which the booklet keeps out of the calculation. Lottery and gambling income, which it excludes by name. And property tax, which runs on a separate set of homestead rules.
Social Security is the useful one. Because it never enters the worksheet, a 65-year-old drawing $30,000 of benefits plus $65,000 from an IRA owes no Georgia income tax on either. The homestead and senior property exemptions, and the separate military retirement rules, are covered in how Georgia taxes retirees.
Where does the exclusion meet a Blue Ridge home purchase?
I’m Thomas Echea, a Luxury Real Estate Advisor with E+E Group at Compass, and I own homes in Blue Ridge and Fort Lauderdale. The exclusion rarely decides whether someone moves. It does shape the details: whose name the income arrives in, which year the old house sells, and how soon the new address becomes the legal one.
Those are CPA questions, and they are cheaper to ask before the closing than after. The carrying cost of the house itself is a separate calculation, set out in Fannin County property taxes and the cost of retiring in Georgia.
Frequently asked questions
How much is Georgia’s retirement income exclusion for 2026?
It is $35,000 per taxpayer aged 62 to 64 and $65,000 per taxpayer 65 or older. A taxpayer under 62 who is permanently and totally disabled also qualifies for $35,000. Under House Bill 463, the amount for taxpayers 65 or older rises to $70,000 for tax years beginning in 2027.
Can married couples combine the Georgia retirement exclusion?
Not by pooling it. Each spouse qualifies separately and applies their own limit to income they own, with jointly held income split 50% to each. Two spouses 65 or older can exclude up to $130,000 between them, but one spouse’s unused room cannot cover the other’s income.
Does Social Security count against Georgia’s retirement income exclusion?
No. Georgia exempts taxable Social Security and Railroad Retirement benefits separately on Schedule 1 of Form 500, and the IT-511 booklet keeps them out of the exclusion calculation. The full $35,000 or $65,000 stays available for pensions, IRA withdrawals, interest, dividends, rent and capital gains.
Is rental income eligible for the Georgia retirement exclusion?
Net rental income qualifies in full. The exception is rental income subject to self-employment tax, which Georgia treats as earned income, and only $5,000 of earned income can use the exclusion. A short-term rental where the owner provides substantial services for guests can land in that category.
Does a Roth conversion qualify for Georgia’s retirement income exclusion?
Yes, for a taxpayer who meets the age or disability test. A conversion is reported federally as a taxable IRA distribution, and taxable IRA distributions sit inside Georgia’s exclusion worksheet. A 66-year-old with $43,000 of unused exclusion could convert that amount with no Georgia income tax, though federal tax still applies.
Do part-year residents get the full Georgia retirement exclusion?
No. Part-year residents and nonresidents must prorate it, with earned and unearned income prorated separately by their Georgia-source share. In the Department of Revenue’s worked example in the IT-511 booklet, a $65,000 maximum becomes $34,785.